Germany has finally woken up and realized that it has largely missed the boat on the digitalization of public services. In the business sector, however, the use of digital applications looks better. Products and processes are increasingly digitalized. But that is not enough! In addition to the demand for digital applications, the supply side of systems must also be considered.
The systems used come predominantly from foreign manufacturers, who thereby drive digital innovation. Due to the high influence of digitalization on the innovative capacity of products and processes, Germany is drifting into a strong dependency. On the provider side, large corporations from America and Asia dominate across hardware, platforms, application software, and services (with the exception of SAP's global success in enterprise software). This is currently being further reinforced by foreign AI giants. The dominance is simultaneously based on a lead in research, where research successes are reflected in new products, which in turn drive new research.
During my four-year term as President of the digitalization association Bitkom from 2007 to 2011, I had set myself the goal of drawing attention to the discrepancy between Germany's success in traditional industries such as automotive, mechanical engineering, etc., and the weakness of the digital industry, and of calling for a catch-up effort. Unfortunately, the annual digital summits became more of a showcase for politicians—from the Federal Chancellor to ministers—than a demonstration of German digital product successes. My call for the development of a German cloud was viewed as a provincial perspective in a global market; after all, Germany was the general world export champion, and we therefore also had to allow other countries their export successes in the digital economy.
However, the importance of digitalization as a decisive driver of innovation and growth across all industries, public services, and private communication has been underestimated. Added to this is the fact that previously friendly partnerships with countries such as the USA and China have shifted into hardened, including political, competitive relationships.
So, the time has come to get started. Germany wants to catch up in terms of application and supply, thereby becoming less dependent on large foreign providers. At the federal level, a Ministry of Digital Affairs has been established—something I had, incidentally, vehemently called for during my time as Bitkom president. This ministry is intended to modernize public services. Companies from the start-up scene, the SME sector, and adjacent disciplines are also getting involved alongside SAP and Telekom in new developments, particularly in the field of artificial intelligence.
The catching-up process of digitalization to achieve greater sovereignty has two dimensions. First, the components of digitalization—from research, hardware, networking, and software platforms to applications and services—must be viewed as an interconnected chain of a sovereign offering. Second, the actors involved in creating this offering, namely research institutes, start-ups, medium-sized enterprises, and large corporations, must be capable and ready to carry out these tasks.
What are the starting conditions for the components and actors? In research, German universities, but above all non-university research organizations such as Max Planck, Fraunhofer, Helmholtz Association, and individual institutes such as the DFKI, represent a genuinely positive factor and have established focal points in current fields such as AI and quantum computing. However, a look at the bibliographies of relevant scientific literature on digitalization reveals hardly any European authors, or only as members of international author teams. In particular, only a few application-oriented research results have manifested themselves in internationally successful products. Unfortunately, the success of MP3 by the Fraunhofer Society has also only led to products outside of Germany.
In all modesty, I may point to my contributions in collaboration with SAP, as well as to the international success of the ARIS concept and the ARIS product that emerged from my research institute at Saarland University. The same applies to my company imc AG, whose products for learning and knowledge management are used internationally. The Hana database of SAP emerged from the Hasso Plattner Research Institute HPI. So it is fundamentally possible, but overall the product success of German research on digitalization, measured against public funding, is too limited.
The state of hardware from German production is almost negligible. Where have the hardware manufacturers of the early days, such as Siemens, Nixdorf, Telefunken, etc., gone? They were all unable to keep pace with the turbulent technological leaps from tubes to transistors to semiconductors, and from mainframes, servers, and PCs to the cloud, and have disappeared from this market segment. The same applies to Europe with providers such as Bull or Philips. The winners have been the American and Asian providers of chips and computers that emerged from start-ups.
As a result, the vast server parks and data centers are also predominantly in foreign hands. The same applies to software platforms consisting of database and workflow systems, even though German systems such as Adabas were once market leaders. The dominance of American and Asian providers of fundamental LLM systems in AI is dramatic. In application software, apart from SAP and a few providers of specialized software, the international comparison also reveals something of a desert.
Here, however, glimmers of hope are emerging for AI applications, as the German industry, for example, possesses a treasure trove of data from its customer applications that can be used for training and applying AI models for industrial companies. The market for the individual development of comprehensive application systems and the digital transformation of large enterprises is largely dominated by foreign companies from the USA as well as by some European companies, for example, from France. No global IT consulting company has established itself from Germany, with the exception of Telekom and T-Systems. This is all the more regrettable, as it would have been possible in the wake of SAP's global success, as their implementer. Some German mid-sized companies that were on the path to internationalization have unfortunately been acquired by international companies and disappeared from the market.
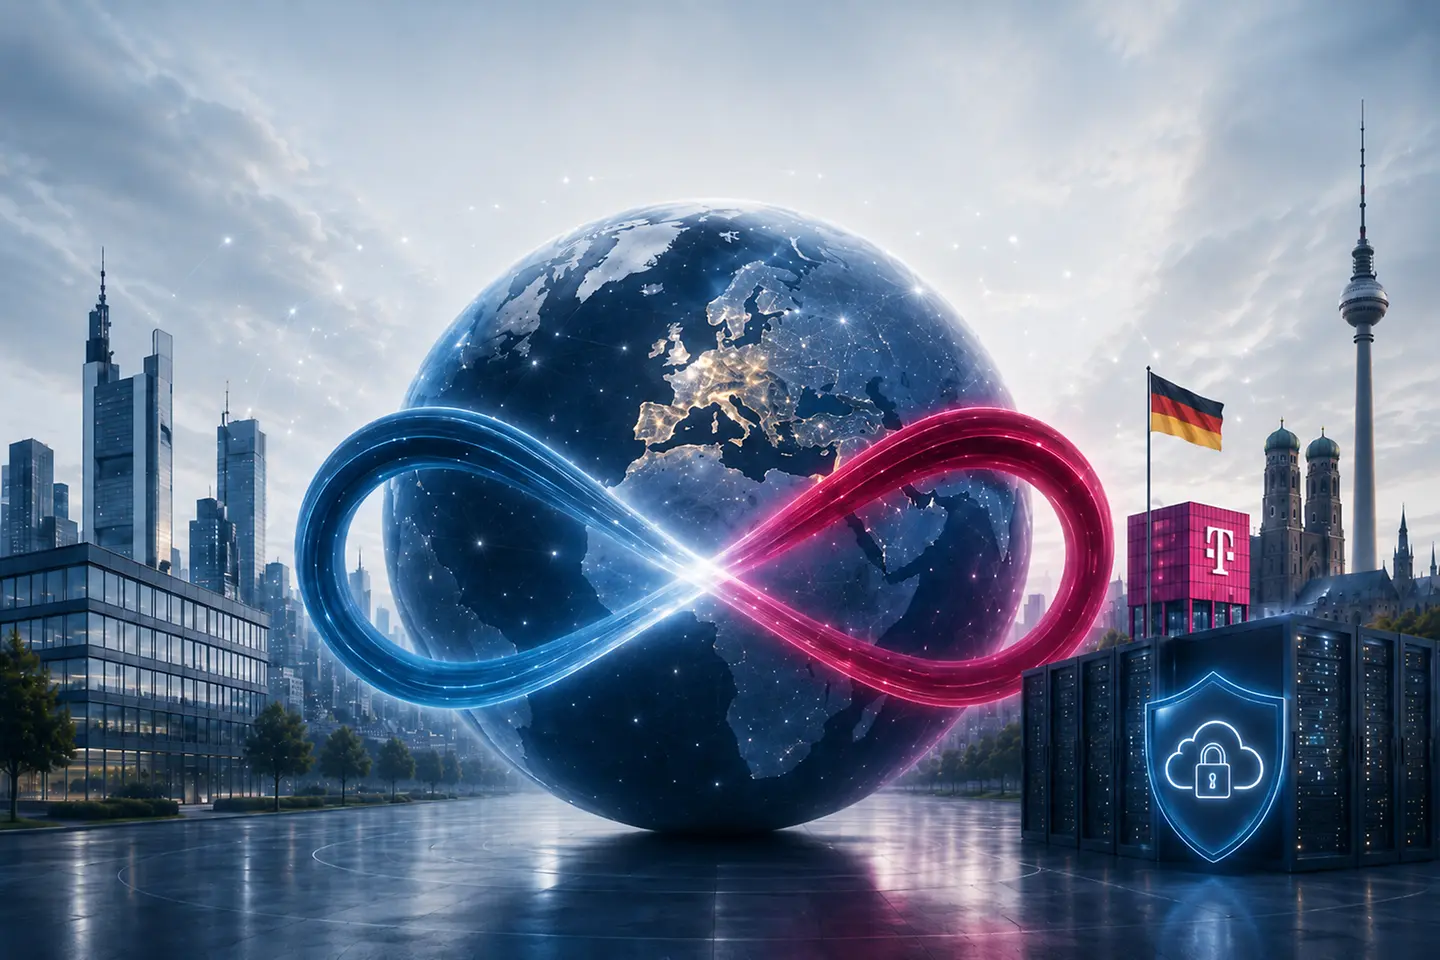
Digital sovereignty does not emerge from individual technologies, but from the interplay of research, infrastructure, platforms, applications, and strong companies.
If efforts are to be made for a fresh start in these fields, the question arises as to whether and how actors can implement them. If digital research at universities and research organizations is to be more strongly directed towards application-oriented output, this requires a cultural shift. Currently, the publication of "papers" dominates as the benchmark for academic success, rather than the translation into successful products. This requires a change in the appointment and hiring policies of institutions in order to attract more entrepreneurially thinking and acting researchers. The research programs Gaia-X, Manufacturing-X, etc., which the Federal Ministry of Economics has equipped with considerable funding in recent years, were well-intentioned and also aimed at strengthening sovereignty, but have barely delivered the expected product successes. Individual lighthouses such as Telekom's investment in the AI factory in Munich are encouraging.
The aforementioned HPI as well as some institutes of the Fraunhofer Gesellschaft also deserve positive mention. The non-profit August-Wilhelm Scheer Institut für digitale Produkte und Prozesse (AWSi), which I founded, likewise follows this application-oriented approach. SPRIND GmbH has been equipped with considerable resources to support breakthrough innovations. There are also individual collaborations between European research institutes, such as between DFKI and the French Inria.
Products can emerge from these research results, particularly through start-ups. However, it must be noted that the survival rate of start-ups is only 20 to 30 percent. Furthermore, many start-ups aim for an early exit from the outset due to the ownership structure of external investors. In many cases, this leads to the most promising start-ups being acquired by large foreign companies, with their technology subsequently taken over by the parent company and largely lost as a growth factor for the domestic location. Conversely, large domestic IT companies are more interested in acquiring "hyped" start-ups in the USA than in giving lesser-known domestic start-ups an opportunity for participation or acquisition. Nevertheless, the start-up scene should be viewed positively for new areas of AI, provided it is supported through cooperation with large companies and through state participation and contracts.
The current mid-sized digital companies in Germany are mainly limited to implementing SAP and predominantly foreign systems from Microsoft or ServiceNow, offering little basis for a sovereignty strategy through new products. However, I succeeded in the 2000s in turning the software product ARIS for business process optimization into a global success with the mid-sized company IDS Scheer AG. With a sufficient innovation lead, a capable team of employees, and ambition, this is therefore possible. That is why we are also making every effort now, during the AI revolution, to achieve similar success with the company Scheer PAS and its namesake product for the development and execution of AI agents.
Since the markets for digital products, from hardware to consulting, are dominated by large international corporations, the key question is whether Germany will succeed in producing comparable companies. Existing telecommunications companies could be a first starting point, given their proximity to the industry.
Deutsche Telekom is currently investing in the construction of high-performance data centers for AI. Even though chips from non-European manufacturers are being used here, an important step in the right direction has been taken in Munich with T-Systems' Industrial AI Cloud. Based on the recognition that Germany possesses deep industrial knowledge and a large industrial dataset, it can achieve a competitive advantage through the training and application of corresponding AI models.
Building on the hardware, a sovereign system is being constructed using the Industrial AI Cloud stack comprising software for security, platform, and AI applications, with predominantly German providers. We are part of the platform and application layer with our product Scheer PAS.
The architecture is designed to support the training of large AI models, industrial simulation, robotics, or digital twins. SAP and Siemens are also involved as large companies on the platform. The federal government and the states are involved for public services. Overall, the combination of many actors provides a starting point for a major step towards the desired sovereignty.
The gap compared to the investments of the US giants in infrastructure is still enormous. It is, therefore, also important that Germany and Europe allow start-ups emerging from research across all fields of digitalization to grow into large companies, without collapsing beforehand or being acquired by foreign companies. This is where the state can help. It is one of the largest customers for digital products and can, therefore, also act as a promoter of companies. Here, it can make valuable contributions through targeted industrial policy and under the professional supervision of a digital ministry. The awarding of development contracts by the American Department of Defense to start-ups was, among other things, an important success factor in the emergence of the Silicon Valley and should serve as an example.
Another important player is the financial system for financing the required corporate growth. Here, in addition to the traditional banking system, the VC scene and state institutions such as KfW should be mentioned. The state then also takes on the role of an entrepreneur through financial equity stakes in companies. This option was recently created by the federal government.
As a guiding principle for shaping genuine digital sovereignty, it must be noted that only a holistic view of the stack of systems—from infrastructure through platforms to applications and consulting—as well as the connection of all actors from research, start-ups, and large companies to the state and the financial system, is a prerequisite for taking measures that lead to true sovereignty. For Germany, this is still a long but achievable path.